Executive condos in Singapore: the 2026 guide
Every executive condominium selling now, plus every parcel in the 2026–2027 pipeline with the land each developer paid. New to ECs? The value maths, the May-2026 rule change and the eligibility check are in the Executive Condo Guide.
Start here
New to ECs? Read the guide first
The background — what the subsidy is actually worth, what the May-2026 rule change costs you, and whether you qualify at all — now lives in one place, so this page can get on with what is for sale.
- The value. New ECs launch roughly $400–$600 psf under a comparable private condo. That gap narrows to about 9% at five years and 5% at ten, once the EC privatises.
- The May-2026 reset. Parcels whose tenders closed from 8 May 2026 carry a 10-year MOP and 15-year privatisation, with the deferred payment scheme removed and 90% of units held for first-timers. Five pipeline parcels — five separate projects — closed before the cutoff and keep the old rules.
- Your eligibility. Two rules decide most cases: the $16,000 income ceiling and the 30-month private-property bar. The ceiling rises to $18,000, but only for ECs on parcels whose tenders close on or after 24 August 2026 — nothing in the list below. Check before you queue for a ballot.
Read the Executive Condo Guide Check your eligibility in 2 minutes
Selling now
ECs you can buy today
Launched, with a real price list and live availability — no modelling required. Ask me for the current unit count before you plan around a specific stack; it moves daily.
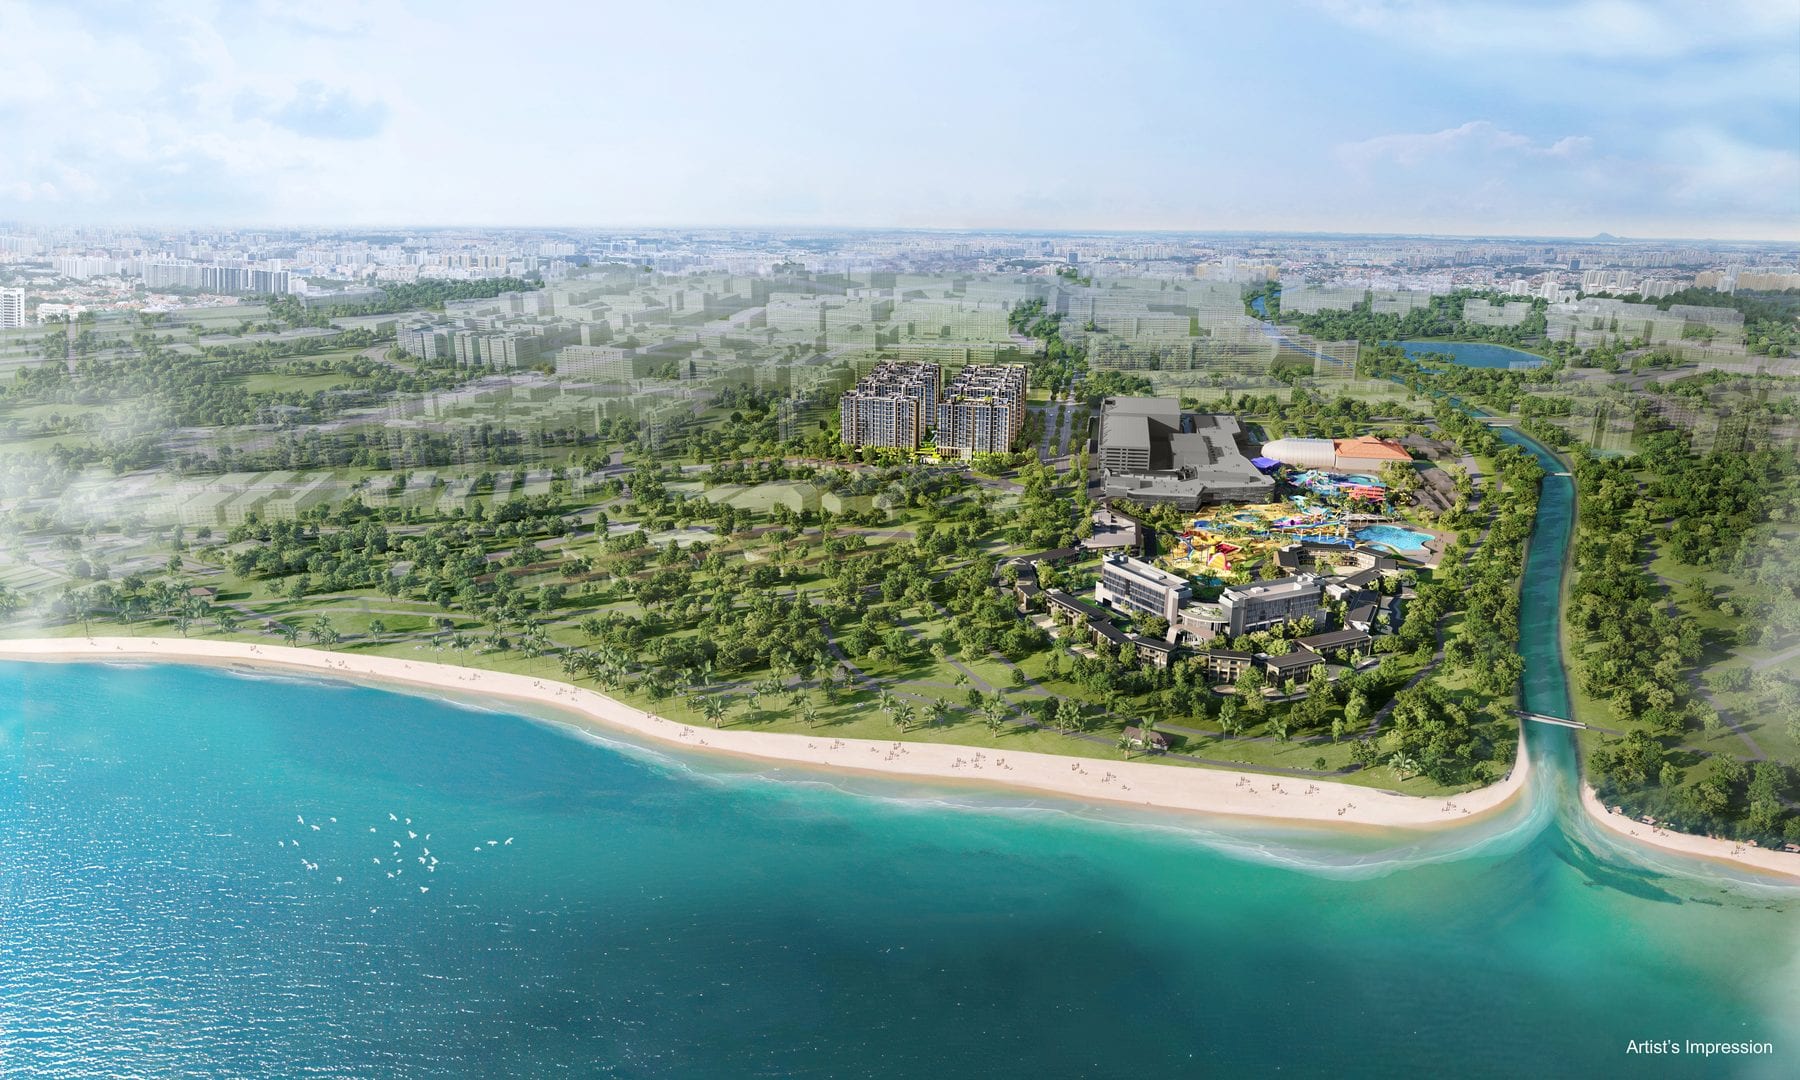
2 parcels · previewing this year
Upcoming EC Launches in 2026
Both sit on the old-rules side of the May-2026 cutoff, so the five-year minimum occupation period and ten-year privatisation still apply — and both are City Developments projects, previewing within weeks of each other.
3 parcels · land awarded, not yet designed
Upcoming EC Launches in 2027
Next year's EC pipeline. Every parcel below has been tendered and awarded, so the land cost is public record, but none has been designed and no developer has released a price list. The third 2027 parcel is Sim Lian's at Woodlands Drive 17: a separate project with its own ballot, but still unnamed, so it shares a page with Wynwood Grand rather than getting a card here. If your household is close to the $16,000 income ceiling, these are the ones worth planning around — the ceiling is tested at application, not at booking.
All 5 parcels
Every upcoming EC, with the land each developer paid
Five parcels, five projects. Woodlands Drive 17 was sold as two parcels to two developers, so until Sim Lian names its project the pair share one page. EC land is sold at a subsidised rate, which is the whole reason the format is good value, and the gap is easy to see side by side: the cheapest private condominium land in the same pipeline is Dairy Farm Walk GLS at $963 psf ppr (URA tender awarded 22 Jan 2026), while every parcel below is under $800.
Source: HDB and URA executive condominium land tenders via the PropNex project register · Land data as at 8 August 2026 · Permalink: vionapropnex.sg/executive-condos/#ec-land-table
| Project | Where · region | Type | Developer | Units | Land $ psf ppr | Expected launch |
|---|---|---|---|---|---|---|
| Solano Grand EC | D23 Bukit Panjang · OCR | EC | City Developments | 300 | $771 | Q4 2026 |
| Wynwood Grand EC | D25 Woodlands · OCR | EC | City Developments | 420 | $782 | Q4 2026 |
| Sembawang Road EC | Sembawang · OCR | EC | Developer not announced | 265 | $692 | Q1 2027 |
| Woodlands Drive 17 EC — Sim Lian parcel | D25 Woodlands · OCR | EC | Sim Lian Land | 560 | $794 | Apr 2027 |
| Miltonia Close EC | D27 Yishun · OCR | EC | Hoi Hup Realty | — | $732 | 3Q 2027 |
Swipe to see all columns →
Full detail on each: the EC pipeline tracker, with tender dates, old-rule versus new-rule status and expected previews. To weigh an EC against a private launch, see the complete project register.
The money
What an EC costs each month, in real dollars
EC loans answer to MSR, the mortgage servicing ratio. Your monthly mortgage cannot exceed 30% of gross household income. At the $16,000 ceiling that cap is $4,800 a month. At a 4% stress rate over 30 years, that is a loan of roughly $1.0M, which supports a purchase of about $1.34M with 75% financing.
A worked example at a $1.35M unit: the 25% downpayment is $337,500, of which at least $67,500 (5% of price) must be cash. The rest can come from CPF. Buyer's stamp duty adds about $38,600. Monthly repayment at the MSR cap is the $4,800 above.
One more line item for first-timers: a CPF housing grant of up to $30,000 exists for EC buyers, but it is income-tested, and most households near the ceiling get little or none. Do not count it until the tier is confirmed against your payslips.
Two things that can shrink those numbers before you get near the ceiling.
- TDSR applies to an EC too. MSR at 30% is the tighter of the two and usually the one that binds, which is why it gets the attention — but the 55% total debt servicing ratio still runs alongside it. A car loan, a personal loan or a second mortgage is counted there and not in MSR, so a household with existing debt can be TDSR-limited well below its MSR ceiling. Whichever cap is lower is your cap.
- The age-65 LTV cliff. The 75% loan-to-value above assumes a 30-year tenure that ends by age 65. If the tenure runs past 65 — or past 30 years — LTV drops to 55% and the cash-and-CPF downpayment jumps from 25% to 45%. On a $1.35M unit that is $607,500 instead of $337,500. EC buyers are typically in their late thirties and forties, so this bites more often here than on a first HDB purchase: a 40-year-old taking 30 years finishes at 70 and is already over the line.
The ceiling moves to $18,000 for new units in ECs built on land-sale parcels whose tenders close on or after 24 August 2026 — the closing date, not the award date, which follows it by weeks. That lifts the MSR cap to $5,400 a month. It does not touch anything on sale today — every project above stays at $16,000, balance units included. Two longer reads: what the $18,000 ceiling actually unlocks, and when, and the launches that will carry it.
The honest read
Who an EC suits, and who should skip it
An EC suits you if your household earns up to $16,000, you want condo facilities without the private-condo price, and you can hold for at least five years past TOP. Upgraders in the north and northwest have the most to gain from this batch: four of the five old-rule projects sit in Woodlands, Sembawang, Yishun and Bukit Panjang.
Skip it if you might need to sell, or rent out the whole unit, within five years. The MOP is not flexible. Skip it too if the 30% MSR maths only works at the smallest unit and your family needs more space. Be honest with yourself on that number before the showflat does its job.
One more thing, said plainly: if you buy through me, the developer pays my commission. You pay nothing extra. My read is written before that consideration, which is why it includes who should skip.
"We had so many doubts about the income ceiling and MSR loan limits. Viona calculated our exact eligible numbers, walked us through the balance-unit purchase at North Gaia, and we got our unit hassle-free."
Questions
EC questions I get every week
A PR can co-apply with a Singapore Citizen within a family nucleus, but at least one applicant must be a citizen. PR-only and foreign households cannot buy a new EC from the developer. Foreigners can only buy ECs that have fully privatised: 10 years after completion for older projects, 15 for newer ones.
Yes, on the five old-rule projects. They keep the 70/30 quota, so 30% of units are open to second-timers at launch. If you have enjoyed a housing subsidy before, a resale levy may apply. Check the levy maths early, because it changes your budget by tens of thousands. New-rule launches reserve 90% of units for first-timers for two years, which makes the old-rule batch your realistic window.
No. Buying a new EC from the developer does not attract ABSD, even if you own an HDB flat. The condition is that you sell your existing flat within six months of collecting your EC keys.
HDB assesses household income at e-application, before the ballot. A pay rise after booking does not take your unit away. If you are close to the ceiling now, get the income maths checked before you apply, because variable pay counts, averaged over 12 months.
No. The HFE letter applies to HDB flat purchases. For an EC you apply through the developer's e-application, and you will want a bank in-principle approval before booking day.
Want the reasoning behind these answers? The full Executive Condo Guide covers what the EC discount is actually worth against a private condo, the May-2026 rule change line by line, and a 2-minute eligibility check that gives you your own answer rather than a general one.
Not sure which EC fits your timeline?
Tell me your situation in two lines: income ballpark, first or second-timer, and which town you're eyeing. I'll tell you which launch to watch, or whether to skip ECs entirely. If a resale condo serves you better, I'll say so.